Of the three goals behind most annuity decisions (protection, accumulation, and income), income is the one that turns savings into a paycheck. And there are two common ways to do it: an income annuity, and an income rider added to a fixed indexed annuity. They can both produce guaranteed income for life, but they work very differently, and the right choice depends on how much flexibility you want to keep.
This guide compares the two side by side, building on the overview in Protection, Accumulation, and Income: The 3 Goals Behind Every Annuity Decision.
How an Income Annuity Works
With an income annuity, you give an insurance company a lump sum, and in return it pays you guaranteed income, often for the rest of your life.
- Immediate income annuities begin paying shortly after you buy them
- Deferred income annuities start paying at a future date you choose, which can mean higher payments for the same amount
The amount of income depends on factors like your age, the size of the lump sum, the payout option you choose, and interest rates at the time. Common payout options include:
- Life only: payments for your lifetime, ending at death
- Joint life: payments that continue for a surviving spouse
- Period certain or refund features: designed to pass something to beneficiaries if you pass away early
The trade-off is that you generally give up access to the lump sum in exchange for the guarantee.
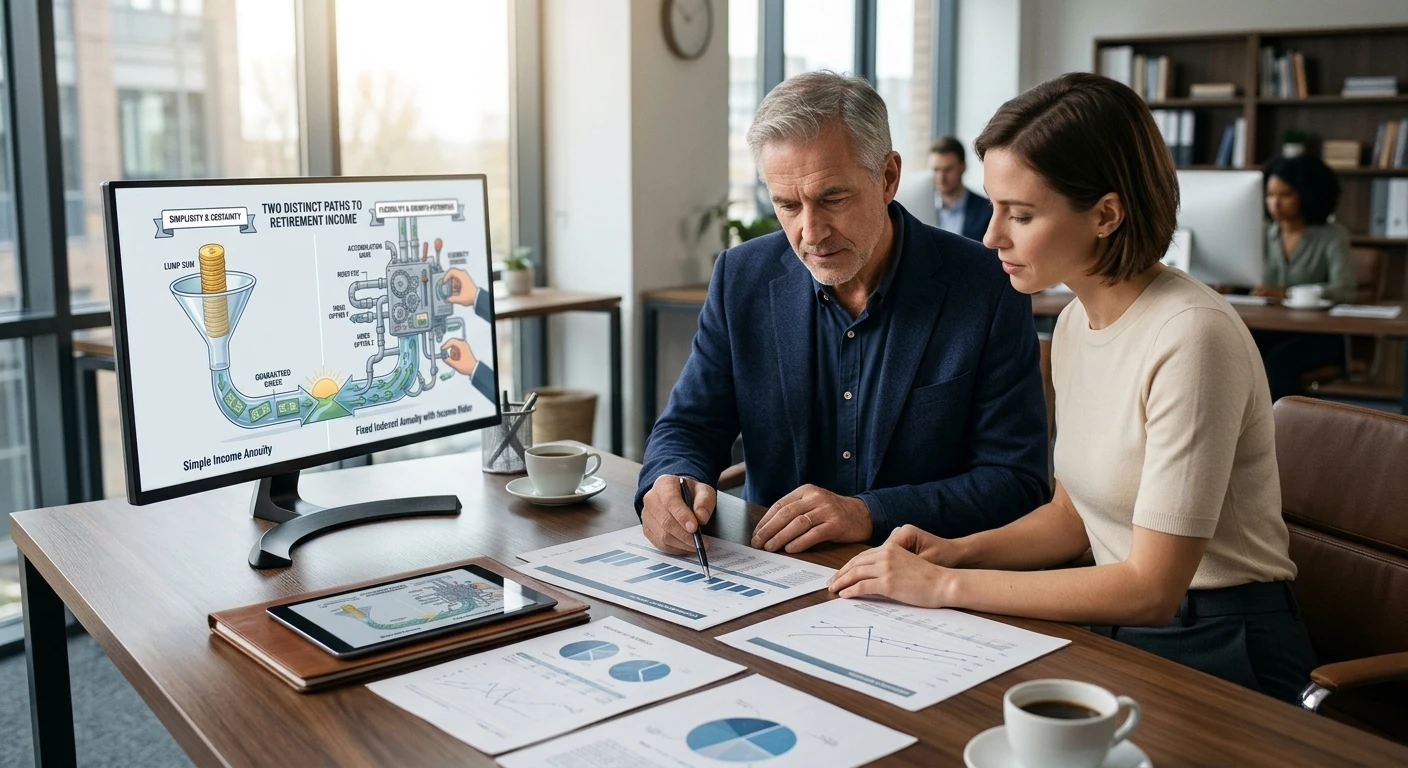
How an Income Rider Works
An income rider is an optional feature added to a fixed indexed annuity. Your money first grows (the accumulation phase), and when you’re ready, you activate the rider to take guaranteed lifetime withdrawals.
A few details matter here:
- The “income base” is not your cash value. Riders typically calculate your guaranteed income from an income base, which is a formula-driven number, not an amount you can withdraw as a lump sum.
- Riders usually carry an annual fee, which can reduce your account value over time.
- Your payout percentage generally depends on your age when you start taking income, and on whether the income covers one person or two.
- You usually keep the remaining account value, which can be accessed subject to the contract’s withdrawal rules and surrender charges.
| Income Annuity | Fixed Indexed Annuity With Income Rider | |
|---|---|---|
| How income is created | Lump sum converted into guaranteed payments | Guaranteed lifetime withdrawals from the annuity once the rider is activated |
| Access to the lump sum | Generally given up | Remaining account value usually stays accessible, subject to contract terms |
| Growth potential before income | Little or none; the purpose is income | Yes, through index-linked crediting during accumulation |
| Cost | Built into the payout rate | Annual rider fee in addition to other contract costs |
| Flexibility on start date | Fixed when you buy (deferred) or immediate | You choose when to activate, within the contract’s rules |
| Complexity | Simpler to understand | More moving parts (income base, rider terms, withdrawal rates) |
| Often used for | Covering essential expenses with certainty | Combining growth potential with a future income guarantee |
Which One Fits Which Situation?
An income annuity may fit if:
- You need income to start soon, or at a specific date
- You want the simplest, most predictable arrangement
- You’re comfortable giving up access to that portion of your savings in exchange for certainty
An income rider may fit if:
- You’re still years away from needing income and want growth potential first
- You want to keep some access to the underlying account value
- You’re comfortable with a more detailed contract and an annual rider cost
Many retirees also use both, with an income annuity covering essential expenses and a fixed indexed annuity providing flexibility for later years.
Questions to Ask Before You Choose
- When do I need the income to start, and can I wait for it to grow first?
- How much of this money might I need access to for emergencies or large expenses?
- What does the rider really cost, and how is the guaranteed income calculated?
- What happens to the income if my spouse outlives me? Joint-life options matter here.
- How will this fit with Social Security and other guaranteed income? Our guide, How Much Retirement Income Do You Actually Need?, can help you size it.
Keep the Fine Print in View
Whichever route you take, remember that guarantees are backed by the claims-paying ability of the issuing insurance company, withdrawals are generally taxed as ordinary income, and early withdrawals may carry surrender charges and, before age 59½, an additional federal tax. Our buyer’s checklist walks through what to review in any contract.
To see how we approach this, visit our pages on guaranteed retirement income planning and personal pension planning.
This article is for general educational purposes and is not tax, legal, or investment advice. Consult a qualified tax professional about your situation. Guarantees are backed by the claims-paying ability of the issuing insurance company. PAG Advisory Group specializes in insurance-based retirement strategies and does not offer securities.
Not sure which income approach fits your plan? Schedule a free retirement review and get a clear, no-pressure comparison based on your own goals.